News #121 - Global Logistics Update: July 17, 2025
Tariff Developments: Escalations and Negotiations Continue
President Trump Expands Reciprocal Tariff Proposals
In the latest series of trade announcements, President Trump has proposed new reciprocal duty rates on additional U.S. trade partners:
Canada: 35%
European Union: 30%
Mexico: 30%
It remains unclear whether imports under the United States–Mexico–Canada Agreement (USMCA) will be exempt. To date, over two dozen tariff letters have been released, with all proposed tariffs scheduled to take effect on August 1, pending confirmation via executive order or Federal Register notice.
The tariff policy stipulates that:
Any retaliatory increase by a partner nation will be matched with an equivalent U.S. tariff increase.
Transshipped goods used to circumvent tariffs will be subject to the highest applicable rate.
All existing reciprocal tariffs will remain in place until August 1, with the exception of China, whose 10% duty is set to expire on August 12.
U.S.–Indonesia Trade Agreement Announced
On July 15, the U.S. and Indonesia finalized a deal setting a 19% reciprocal tariff, scaling back from the previously proposed 32%.
EU Postpones Retaliatory Measures
In response to the proposed 30% U.S. tariff, the European Union announced a delay in its planned retaliatory tariffs, opting to pursue bilateral trade negotiations through early August.
New Trade Investigations and Tariff Proposals
Brazil: The USTR initiated a Section 301 investigation into Brazil on July 15, focusing on digital trade policies, tariff frameworks, and anti-corruption measures. A 50% reciprocal tariff has been proposed.
Vietnam: Announced on July 2, a 20% tariff will be applied, alongside a 40% duty on transshipped goods.
BRICS Nations: A universal 10% tariff is planned on imports from BRICS countries (Brazil, Russia, India, China, and others), in addition to any existing tariffs.
Pharmaceuticals: A proposed tariff of up to 200% is under consideration, with a one-year grace period for companies to onshore production.
Copper: A 50% import tariff will take effect August 1 following a Commerce Department national security review.
Ocean Freight Market Overview
Trans-Pacific Eastbound (TPEB)
Capacity & Demand
Demand remains stable but flat through July and August.
Carriers report 80–90% deployment in July, tapering to 75–86% in August amid persistent overcapacity.
Congestion in Malaysia and Singapore has caused 3–5 day delays for Southeast Asia–origin services.
Equipment Availability
Equipment levels are sufficient across most TPEB origins.
Rates
West Coast: GRIs (General Rate Increases) were implemented by some carriers as of July 15; others extended rates or applied “bullet” spot rates.
East Coast & Gulf: GRIs and PSSs (Peak Season Surcharges) have been mostly mitigated for the rest of July.
Far East Westbound (FEWB)
Capacity & Demand
Weekly capacity has increased by 19% MoM, now averaging 306,100 TEUs.
Week 29 blank sailings led to significant cargo backlogs.
Peak season demand has exceeded expectations and is likely to extend beyond typical timelines.
Equipment
Rollovers and strict equipment controls persist.
Alternative routings via extra loader vessels (e.g., Gemini) may add 2–4 weeks to ETAs.
OA and PA alliances are limiting bookings through Weeks 31–32.
Rates
Freight rates remain stable. The SCFI (Shanghai Containerized Freight Index) stands at $2,099/TEU, reflecting slight downward pressure on further GRIs.
External Risk Factors
Red Sea Security: Renewed Houthi attacks eliminate Red Sea routing as a near-term option.
U.S.–EU Tariffs: The proposed U.S. tariffs may affect European manufacturing demand but will likely spare consumer goods-focused Asia–Europe trade in the short term.
Trans-Atlantic Westbound (TAWB)
Capacity & Demand
PSA Antwerp: 8-day dwell times persist.
Ports in Hamburg, Bremerhaven, and Rotterdam report 3–4 day delays.
Export demand from Germany, Benelux, and Spain is increasing.
Only ~5% of sailings are blanked, indicating market stability.
Equipment
Austria, Slovakia, Hungary, and Southern/Eastern Germany are experiencing container shortages.
Portugal is facing imbalance issues.
Rates
July PSSs have been postponed. Rates are expected to remain stable through Q3.
Indian Subcontinent to North America
Capacity & Demand
Peak season has begun, with added capacity to the U.S. East Coast.
Some services are bypassing Charleston to improve schedule reliability.
West Coast capacity has expanded, partly due to spillover from TPEB lanes.
Rates
East Coast: GRIs and PSSs were announced but not fully implemented; rates vary significantly based on utilization.
West Coast: GRIs did not hold; PSSs have declined.
Pakistan: Continued elevated costs and delays due to India–Pakistan routing constraints.
Air Freight Update – Week 27 (June 30–July 6, 2025)
Volume and Rate Trends
Global volumes fell 3% WoW, driven by an 11% decline in North America due to the Independence Day holiday.
Global rates rose 2% WoW, led by strength in Asia-Pacific lanes.
Key Lane Performance
China & Hong Kong to Europe: Volumes surged 15% YoY, reaching their 2025 peak.
Asia-Pacific to U.S.: Volumes dipped 3% WoW, but rates rose 3% WoW.
Market Drivers
Pre-tariff frontloading activity remained limited ahead of the August 1 tariff implementation.
Capacity shifts and trade re-routing—especially due to de minimis regulation changes and e-commerce strategy shifts—continue to influence Asia-Pacific flows.
(Source: WorldACD)
Ocean Timeliness Indicator – Week Ending July 14, 2025
China to U.S. West Coast: Transit time increased by 1 day (from 37.1 to 38.1 days).
China to North Europe: Transit time improved by 2.3 days (from 60 to 57.7 days).
China to U.S. East Coast: Transit time increased by 0.8 days (from 50.8 to 51.6 days).
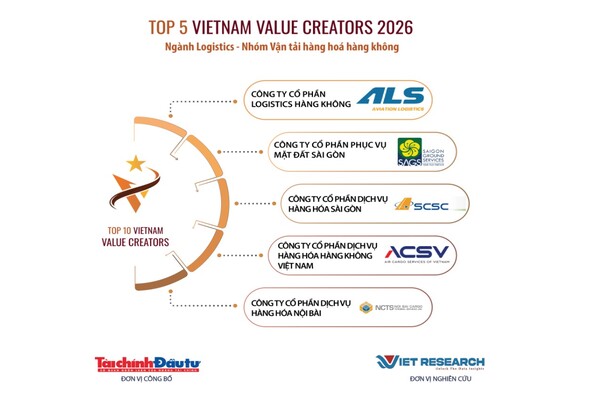
ALS Named Among Vietnam’s Top 5 Value-Creating Enterprises in Air Cargo Transportation...
ALS Aviation Logistics Corporation (ALS) has been recognized among Vietnam’s Top 5 Value-Creating Enterprises in 2026 (VALUE10) in the Logistics Industry – Air Cargo Transportation...
News #202637 - DHL Express revenue up nearly 20 percent year on year in Q3
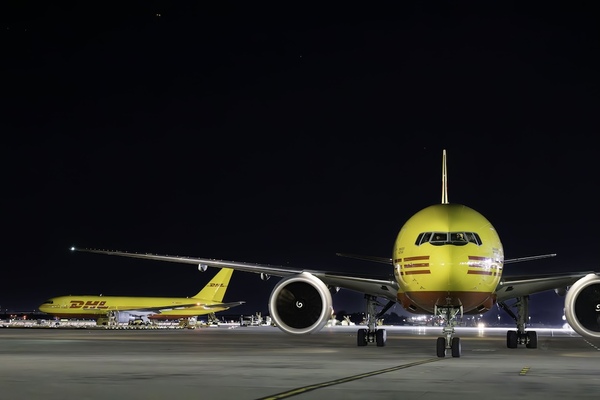
DHL Group has announced its Q3 results, as all divisions together report a 12.6 percent growth in revenue. This comes in at €22.7 billion, up from €20.1 billion in 2025
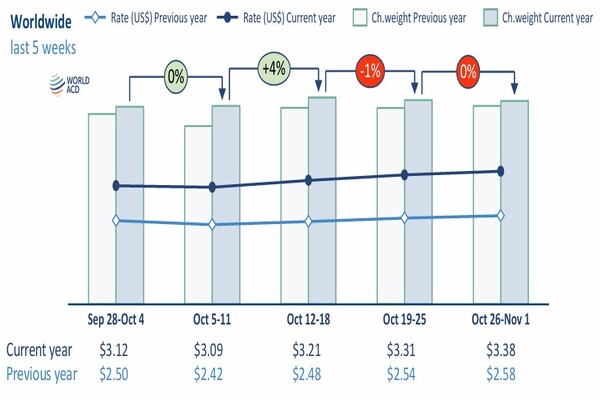
News #202637 -WorldACD: Tonnages up +6% in October despite drop in China-Europe volumes
Global air cargo tonnages in October grew by +6% compared with their level this time last year, according to the latest figures from WorldACD Market Data, as growth in most...
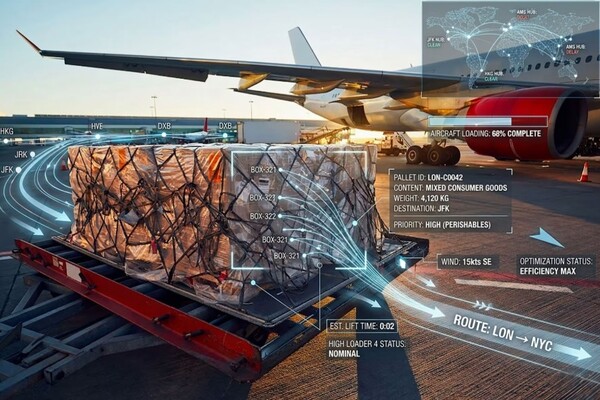
News #202636 -Air cargo cashes in on Al boom - but who has the edge?
There is no shortage of companies enjoying the Al boom - from airports to airlines and forwarders, the latest airfreight trend is filling both aircraft and coffers - but companies...
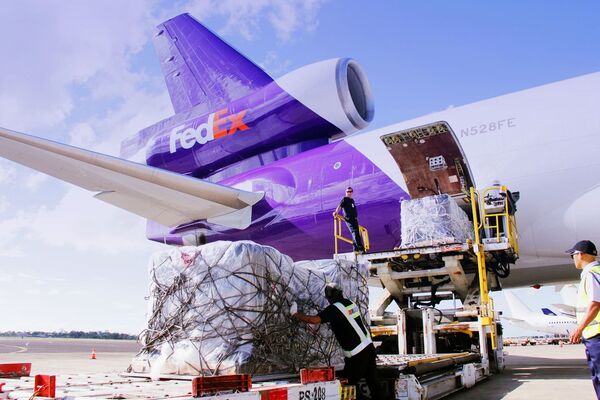
News #202636 -FedEx adds trans-Pacific freight capacity for manufacturers
FedEx has expanded trans-Pacific airfreight capacity for industrial supply chains. Five weekly Boeing 777F flights add a stated 567,000kg of capacity, with links through Asian...
News #202636 -Vietnam Logistics Forum 2026 to seek measures for central region's products...
The forum will provide a platform to discuss measures for developing the logistics sector amid changing domestic and international conditions, enhancing economic competitiveness,...
News #202636 - IATA - Air Cargo Demand Accelerates in September, Up 7.7%
Air cargo demand rose 7.7% year-on-year in September, with growth across all regions. Stronger global trade and manufacturing provided a supportive backdrop, while AI-related...
News #202636 - Vietnam’s trade surpasses $1tn in 10 months
Vietnam’s total goods trade reached an estimated US$1.01 trillion in the first 10 months of 2026, up 32.3 per cent from a year earlier, surpassing the $1 trillion mark for...
News #202636 - Air cargo growth masks freighter squeeze as fuel price outpaces yields
Rising airfreight yields have failed to keep pace with soaring fuel prices, squeezing freighter economics despite a sustained period of strong demand growth, according to...